VA Home Loans in California
You earned this benefit. Let’s use it well.
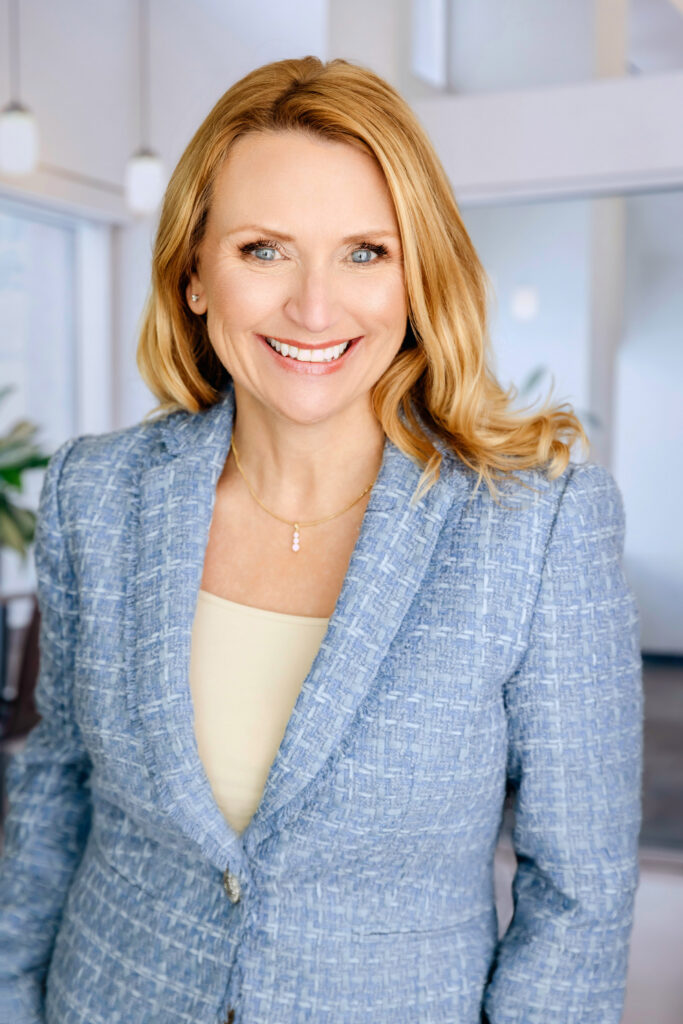
I’m Fiona Bryan, a mortgage advisor in Southern California. I help veterans and military families buy homes with a plan behind them, not just a loan.
For veterans, active duty service members, Guard and Reserve members, and surviving spouses, from the South Bay and Los Angeles Air Force Base to all over California.
No monthly mortgage insurance
No VA loan limit with full entitlement
A benefit you can use more than once
Why I do this
Why I care about getting this right for veterans
Before I was a lender, I spent years in the nonprofit world, and I still serve on several nonprofit boards. I’ve worked alongside a lot of people who give their time to something that matters. Military service is that on a scale most of us can’t imagine. So when a veteran sits down with me, I want their home loan benefit to work as hard for them as they worked to earn it.
Here’s what I see too often. A veteran gets steered into a conventional loan because someone said sellers don’t like VA offers. Or they assume they used their benefit once and it’s gone. Or nobody explains that the VA loan can be part of a longer plan. I’d rather sit down, run the numbers both ways and show you what you actually have.
I’ve lived in Southern California for 15 years and raised my three kids here. I lend all over California, and I stay in touch after closing with regular check-ins on your loan. Think of me as your lender for life, not just for this house.
VA loans at a glance
What is a VA loan? A VA loan is a home loan for eligible veterans, service members and some surviving spouses. It’s made by a private lender like Empire Home Loans and guaranteed by the U.S. Department of Veterans Affairs.
- Upfront cash: Built to keep it low. Ask me what you’d need.
- Monthly mortgage insurance: None
- Loan limit: No VA limit with full entitlement
- Funding fee: One-time fee for most borrowers. Veterans receiving VA disability compensation are exempt.
- Property: Must be your primary home. Up to four units allowed if you live in one.
- Reusable: Yes, the benefit can be used more than once.
Last updated: October 2026
Your benefits
What are the benefits of a VA loan?
These benefits come from your service. Nobody’s doing you a favor here. You earned every one of them.
Keep more of your savings
VA loans are built to lower the cash you need upfront, which matters a lot in a California price range. I’ll walk you through exactly what you’d bring to closing.
No monthly mortgage insurance
Most loans with a small down payment add mortgage insurance to your payment every month. VA loans don’t. Over the years you own the home, that adds up to real money.
No VA loan limit with full entitlement
If you have your full entitlement, the VA doesn’t cap how much you can borrow. In Southern California, that’s a big deal. You still need to qualify for the payment.
Help with closing costs
VA rules limit some of the fees a veteran can be charged. Sellers can also pay some or all of your closing costs, and I’ll help your agent ask for it.
A funding fee you might not owe
Most VA loans have a one-time funding fee that you can roll into the loan. If you receive VA disability compensation, you’re exempt. I check this on every file so nobody pays a fee they don’t owe.
An approval that looks at the whole person
VA guidelines look at your full financial situation, not just one number. Military life means moves, deployments and gaps on paper. That’s normal, and it’s worth a conversation.
Strategy over rate
How to get the most out of your VA loan
Most lenders stop at getting you approved. I care more about where you’ll be in ten years. A good rate on the wrong plan costs more than people think, and your VA benefit is too valuable to use without one.
Can you use a VA loan more than once?
Yes, and this surprises a lot of people. Once a VA loan is paid off, your entitlement can usually be restored. In some cases, you can keep your first VA home as a rental and use your remaining entitlement to buy the next one.
Can you buy a duplex or fourplex with a VA loan?
Yes. You can buy a property with up to four units as long as you live in one. Your tenants help cover the mortgage, and in many cases their rent can help you qualify. In Southern California, it’s an option worth a serious look if you want your home to help build long-term wealth.
When should you refinance a VA loan?
VA offers a streamlined refinance for lowering your rate and a cash-out refinance for tapping equity. I’ll tell you honestly when a refinance pays off and when it doesn’t. That’s part of the regular check-ins I do with every client after closing.
What happens when you sell a home with a VA loan?
A qualified buyer can take over your VA loan, which can make your home stand out if rates have gone up. There are tradeoffs with your entitlement, and I’ll walk you through them before you decide.
Is a VA loan always the best choice?
Not always, and I’ll tell you if it isn’t. If you’re putting a lot down and don’t qualify for the funding fee exemption, a conventional loan can sometimes cost less. I’ll run both so you see the numbers side by side.
Veterans 62 and older
If you own your home and you’re 62 or older, a reverse mortgage might be worth a look. Learn how reverse mortgages work.
Eligibility
Are you eligible for a VA loan?
You may qualify if you’re a veteran, on active duty, or a current or former member of the National Guard or Reserve. Some surviving spouses qualify too. The service time you need depends on when and how you served, so the easiest way to know is to check.
Getting your Certificate of Eligibility (COE)
The COE shows that you qualify. I can request it for you, or you can get it yourself on VA.gov. Veterans usually need a copy of their DD-214, and active duty service members need a statement of service from their commander.
The process
How does the VA loan process work?
Here’s what to expect from our first call to the day you get your keys, and after.
- Strategy call. We talk about your goals, your budget and how the VA loan compares with your other options.
- COE and pre-approval. I pull your COE, review your paperwork and give you a pre-approval you can shop with.
- House hunting. You shop with your agent. If you don’t have one yet, I can introduce you to agents who know how to write a strong VA offer.
- Your offer. I call the listing agent before you submit so the seller knows your financing is solid.
- VA appraisal. A VA appraiser checks the home’s value and makes sure it meets basic safety standards. I’ll tell you what to watch for before you make an offer.
- Underwriting and closing. I keep you and your agent updated through every milestone until you have the keys.
- After closing. I check in periodically to see if a refinance, an equity move or your next purchase makes sense.
Common worries
What you may have heard about VA loans
Most of what keeps veterans from using their benefit is old information. Here’s what’s actually true.
“Sellers won’t accept a VA offer.”
There are misconceptions around this loan, but a strong pre-approval and a lender who calls the listing agent go a long way. I make that call on every offer.
“The VA appraisal will kill the deal.”
The appraisal checks value and basic safety, like working utilities and a sound roof. If the value comes in low, there’s a process that lets us send the appraiser more sales data before it’s final. This is no different from any other appraisal process.
“I already used my benefit.”
You might have entitlement left, or you might be able to get it restored. It’s worth checking before you rule it out.
“The funding fee makes it too expensive.”
It’s a one-time fee, and it can be rolled into the loan. Many veterans with a disability rating don’t pay it at all. For a lot of buyers, it still costs less over time than monthly mortgage insurance on another loan.
“VA loans take forever to close.”
Most delays come from missing paperwork. I gather what we need upfront and close VA loans just as quickly as any other loan.
For real estate agents
Have a VA buyer? I’ll help you win the offer.
I call the listing agent before your buyer submits, explain how the VA loan works, and answer the seller’s questions so your offer gets a fair look. During escrow, you’ll hear from me every week, and I’ll prep you and your buyer for the appraisal so nothing comes as a surprise.
FAQ
VA loan questions I hear most
Tap a question to see the answer.
What is a VA loan?
A VA loan is a home loan for eligible veterans, service members and some surviving spouses, guaranteed by the U.S. Department of Veterans Affairs. Private lenders make the loan, and the VA guarantee lets them offer strong terms with no monthly mortgage insurance.
How much can I borrow with a VA loan in California?
With full entitlement, there’s no VA loan limit in California or anywhere else. What you can borrow depends on your income, debts and credit.
Do I need a down payment for a VA loan?
It depends on your entitlement and the price of the home. Many VA buyers bring less cash to closing than they expected. I’ll tell you exactly where you stand.
What credit score do I need for a VA loan?
The VA doesn’t set a minimum credit score, but lenders do. A quick call is the easiest way to find out where you stand.
Can I use a VA loan more than once?
Yes. Your entitlement can be restored after a VA loan is paid off, and some veterans have enough left to buy again while keeping their first home.
Can I use a VA loan for a rental property?
No, the home has to be your primary residence. You can buy a property with up to four units, though, live in one and rent out the others.
Can I buy a condo with a VA loan?
Yes, if the condo project is VA-approved. I check the building before you make an offer so there are no surprises.
Can a surviving spouse get a VA loan?
Some surviving spouses qualify, depending on the circumstances of the service member’s death. I’m glad to help you find out.
Do I have to pay the VA funding fee?
Most VA borrowers pay a one-time funding fee, which can be added to the loan. Veterans who receive VA disability compensation are exempt. See the VA’s funding fee details.
Do National Guard and Reserve members qualify?
Yes, if you meet the service requirements. The rules depend on how long and when you served, and I can check your eligibility for you.
Do I need a VA loan officer near me?
Not necessarily, but it helps to work with someone who knows your local market. I’m based in Southern California and work with veterans across the South Bay, Los Angeles County and all of California.
You served. Now let me do some of the work for you.
Let’s sit down for 30 minutes and look at what your VA benefit can do, today and down the road. There’s no credit check and no sales pitch. I’ll explain your options in plain English, and you’ll leave knowing your next step, whether that’s with me or not.
Fiona Bryan is a mortgage advisor with Empire Home Loans (NMLS #1812932), based in Southern California and lending across California since 2019.
Fiona Bryan and Empire Home Loans are not affiliated with or endorsed by the U.S. Department of Veterans Affairs or any government agency.